Foreign Investors Pull ₹13,138 Crore From Indian Stocks in Two Weeks — What Changed So Quickly?
Foreign investors have returned to selling Indian shares after a brief two-month revival in overseas demand.
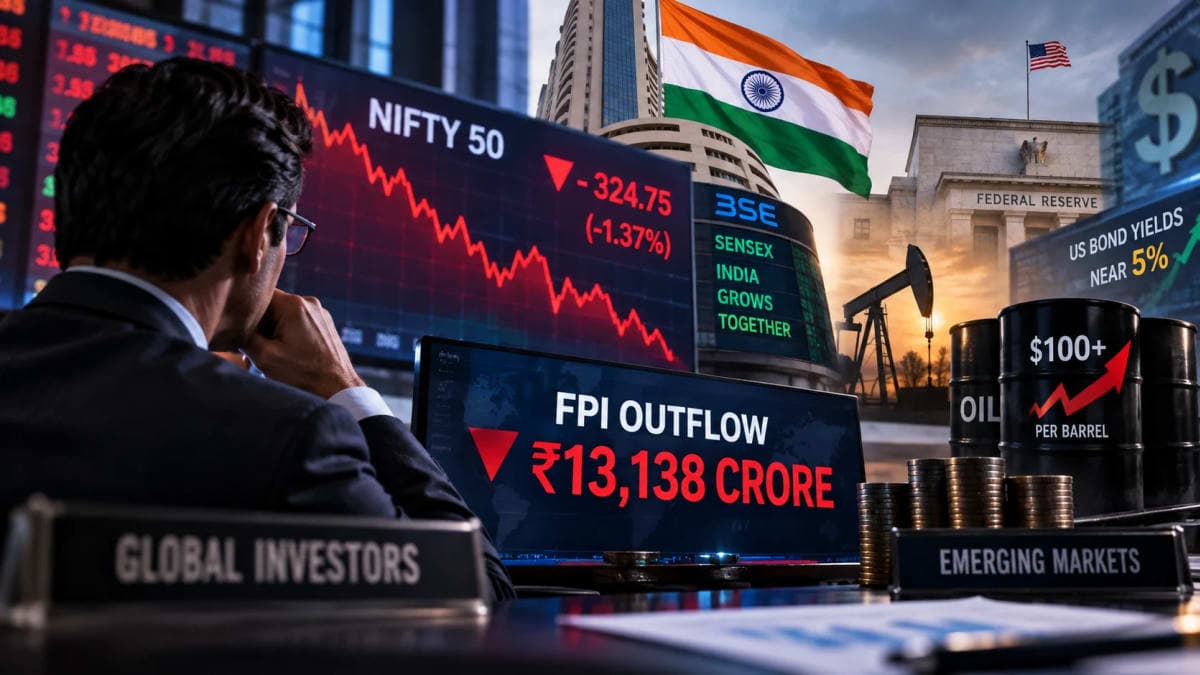
Foreign portfolio investors, or FPIs, withdrew a net ₹13,138 crore from Indian equities during the first two weeks of September 2026, through September 11, according to depository data cited in current market reports. That follows net investments of ₹20,200 crore in July and ₹29,630 crore in August.
The reversal has come as global conditions have turned sharply less favourable for risk assets. Oil has moved back above $100 a barrel, U.S. bond yields have risen towards multi-year highs and the dollar has strengthened as markets prepare for the possibility of tighter U.S. monetary policy.
For India, those pressures matter more than the ₹13,138 crore number alone.
FPIs Have Reversed Two Months of Buying
Foreign investors had only recently started returning to Indian equities.
After four consecutive months of selling between March and June, FPIs invested ₹20,200 crore in July and ₹29,630 crore in August, according to data reported from CDSL.
September has interrupted that recovery.
Through September 11, foreign investors had removed ₹13,138 crore from equities. Year-to-date withdrawals have consequently climbed to about ₹2.37 lakh crore.
That is already substantially above the roughly ₹1.66 lakh crore withdrawn during the whole of 2025.
The comparison matters because it shows that September is not an isolated episode. Foreign investors have been cautious on India for much of 2026, even though there have been periods of renewed buying.
Why Are Foreign Investors Selling Indian Stocks Again?
The immediate pressure is coming largely from outside India.
Three factors have moved together: oil, U.S. bond yields and the dollar.
Oil is back above $100
Brent crude climbed sharply in September as conflict in the Middle East intensified and threats to important energy supply routes increased.
Brent reached $109.97 a barrel on September 11, according to reporting on the FPI data. Oil remained above $100 as fresh attacks and supply concerns continued.
That is particularly relevant for India because it is a major crude importer.
Higher oil prices can increase India's import bill, add to inflation pressure, hurt the rupee and raise costs for companies that depend heavily on fuel or petroleum-linked inputs.
For foreign investors, that can change the risk-reward calculation for Indian assets.
US bond yields are offering tougher competition to stocks
The U.S. 10-year Treasury yield has moved close to 5%, levels that make relatively safer dollar-denominated bonds more attractive compared with riskier emerging-market equities.
When bond yields rise, global investors do not necessarily need to accept as much equity risk to earn an attractive return.
That can pull capital away from markets such as India.
The dollar has strengthened
A stronger U.S. dollar creates another complication.
Foreign investors measure their eventual returns in their home currency. If the rupee weakens while an investor owns Indian shares, part of the equity return can disappear when the investment is converted back into dollars.
The dollar strengthened again on September 14 ahead of major central-bank decisions, with markets assigning a high probability to a Federal Reserve rate increase.
Put together, high oil prices, attractive U.S. bond yields and a firm dollar create an unusually difficult combination for emerging markets.
This Is Not Simply an “India Is Losing Confidence” Story
The size of the foreign withdrawal can make the situation look more straightforward than it is.
Some analysts cited in the reporting argue that the September move is being driven predominantly by global conditions rather than a sudden deterioration in India's domestic fundamentals.
Trackk co-founder and CEO Vedant Gupte described it as a “dollar-and-crude story, not an India story.”
There is evidence supporting that broader interpretation.
Global equity funds recorded large withdrawals in the week ended September 9 as rising oil prices revived inflation fears. Emerging-market equity funds also moved into net outflows after an eight-week run of inflows.
So India is being affected by a wider reassessment of risk, even though country-specific factors still influence where investors allocate money.
India Has One Extra Vulnerability: Expensive Oil
The global sell-off does not affect every emerging economy equally.
India's dependence on imported energy makes a sustained oil spike especially important.
Expensive crude can work through the economy in several ways. It can increase import costs, pressure the current account, weaken the rupee and make inflation harder to control. Companies that cannot pass higher energy and transport costs to consumers may also see margins squeezed.
The stock market has already reacted to those concerns.
On September 11, the Nifty 50 closed at 23,398.10, down 0.34%, while the Sensex ended at 74,781.76, down 0.16%. Both benchmarks had fallen more than 2% during the week and had recorded a fifth consecutive weekly decline.
Those market losses cannot be attributed solely to FPI selling. Oil, monetary-policy expectations, global risk aversion and company-specific developments were also influencing prices.
The ₹13,138 Crore Figure Needs One Important Explanation
Investors comparing different market websites may notice what appears to be contradictory data.
Depository-based FPI figures show a ₹13,138 crore equity outflow through September 11.
Yet provisional NSE cash-market figures for September showed a small positive month-to-date FII balance of about ₹579 crore through the same trading date.
Both numbers can exist because they measure different things.
The broader FPI statistics compiled through depositories include investment activity beyond only the secondary-market cash trades captured in daily exchange FII/DII reports. The datasets therefore should not be used interchangeably.
For readers tracking foreign investment trends, depository data is more appropriate when discussing the headline monthly FPI flow. Daily NSE figures are useful for understanding institutional buying and selling in the exchange cash market.
That distinction is often lost when FPI and FII data are discussed as though every published number measures the same activity.
Domestic Money Is Providing a Powerful Counterweight
One of the biggest differences between today's Indian market and earlier periods of heavy foreign selling is the scale of domestic capital.
Indian investors continue to direct substantial sums into mutual funds.
Equity mutual fund inflows increased 18.8% month-on-month to ₹29,329 crore in August, while gross contributions through systematic investment plans reached a record ₹32,297 crore. Equity funds have now recorded net inflows for 66 consecutive months.
Domestic institutional investors have also remained active buyers in the cash market.
Through September 11, provisional exchange data showed DIIs had purchased a net ₹24,987 crore of Indian shares during the month.
SEBI data separately showed mutual funds themselves were net buyers of equities in early September.
That domestic liquidity does not make Indian stocks immune to overseas selling. But it can absorb part of the supply that FPIs put into the market.
This helps explain why a large foreign outflow no longer automatically produces the sort of market dislocation it might have created when India was more dependent on foreign institutional money.
FPIs Are Not Only Selling Stocks
Foreign investors also reduced exposure to parts of India's debt market during the period.
Reported figures show FPIs withdrew approximately ₹1,350 crore through the Fully Accessible Route and about ₹955 crore through the general debt route, while investing roughly ₹29 crore through the Voluntary Retention Route.
That reinforces the role of global interest rates.
When U.S. government bonds offer higher yields, investors reassess not only emerging-market stocks but also fixed-income allocations.
Is ₹13,138 Crore a Huge Outflow?
It is meaningful, but it needs context.
The September withdrawal is less than half the net amount FPIs invested in Indian equities during August alone.
Foreign investors put roughly ₹29,630 crore into equities in August and then pulled ₹13,138 crore out during the first two weeks of September.
So September has reversed part, but not all, of the previous month's buying.
The more significant number is the ₹2.37 lakh crore year-to-date equity outflow.
That shows that the two-month July-August buying period represented a temporary improvement within a much more cautious year for foreign investors.
Why Can Stocks Fall Even When Domestic Investors Are Buying?
Stock prices are determined at the margin.
If foreign institutions sell large positions in heavyweight companies, those sales can pressure major indices even while domestic funds are buying elsewhere.
Foreign investors also tend to own significant positions in large liquid companies, making their trading particularly influential in the Nifty and Sensex.
Domestic flows can soften the impact without necessarily pushing indices higher.
The September market demonstrates that dynamic: strong domestic buying has coexisted with weak benchmark performance because the broader environment has remained difficult.
Should Retail Investors Be Worried About FPI Selling?
FPI flows are worth monitoring, but they should not become a standalone buy-or-sell signal for long-term investors.
Foreign investors frequently change allocations in response to global interest rates, currencies, commodity prices and relative valuations across countries. Those decisions can have little to do with the long-term prospects of an individual Indian company.
For retail investors, a more useful question is whether the factors driving the outflow are changing India's earnings outlook, inflation environment or individual companies' fundamentals.
A sustained oil shock, for example, would be more important than one fortnight's FPI number because it could eventually affect inflation, monetary policy and corporate profits.
Investors should also distinguish between broad index weakness and company-specific deterioration.
What Could Bring Foreign Investors Back?
Several conditions could improve the environment.
The most immediate would be a decline in crude oil prices.
Lower oil would reduce one of India's largest external vulnerabilities and ease pressure on inflation expectations and the rupee.
A retreat in U.S. Treasury yields could also make emerging-market equities relatively more attractive again.
Foreign flows may additionally respond to Indian corporate earnings, valuation levels and the trajectory of domestic economic growth.
There is recent evidence that overseas investors can reverse course quickly. FPIs bought Indian equities in both July and August before returning to selling in September.
That makes current flows highly sensitive to the macro environment rather than a one-way structural exit.
The Next Big Trigger Is the Federal Reserve
The Federal Reserve's next policy decision is one of the most important immediate events for global markets.
After stronger-than-expected U.S. inflation data, markets were pricing an 86% probability of a Fed rate hike in the week beginning September 14. The U.S. 10-year Treasury yield was hovering near 4.97%.
If rates and bond yields rise further, global investors may have even less incentive to hold riskier emerging-market assets.
Geojit Investments Chief Investment Strategist V.K. Vijayakumar warned that a move in the U.S. 10-year yield towards 5% could increase pressure on global equities and encourage FPIs to shift more capital into higher-yielding bonds.
Oil remains the other major variable.
Brent was trading above $107 on September 14 after renewed attacks on Saudi infrastructure and shipping-related tensions in the Middle East added to supply concerns.
For Indian markets, the combination of those two indicators may matter more in the short term than the ₹13,138 crore already withdrawn.
The foreign selling tells investors what has happened.
Oil and U.S. yields may determine what happens next.