India’s listed new-age technology sector ended a volatile week with a substantial erosion in market value, driven largely by a sharp sell-off in insurance technology companies.
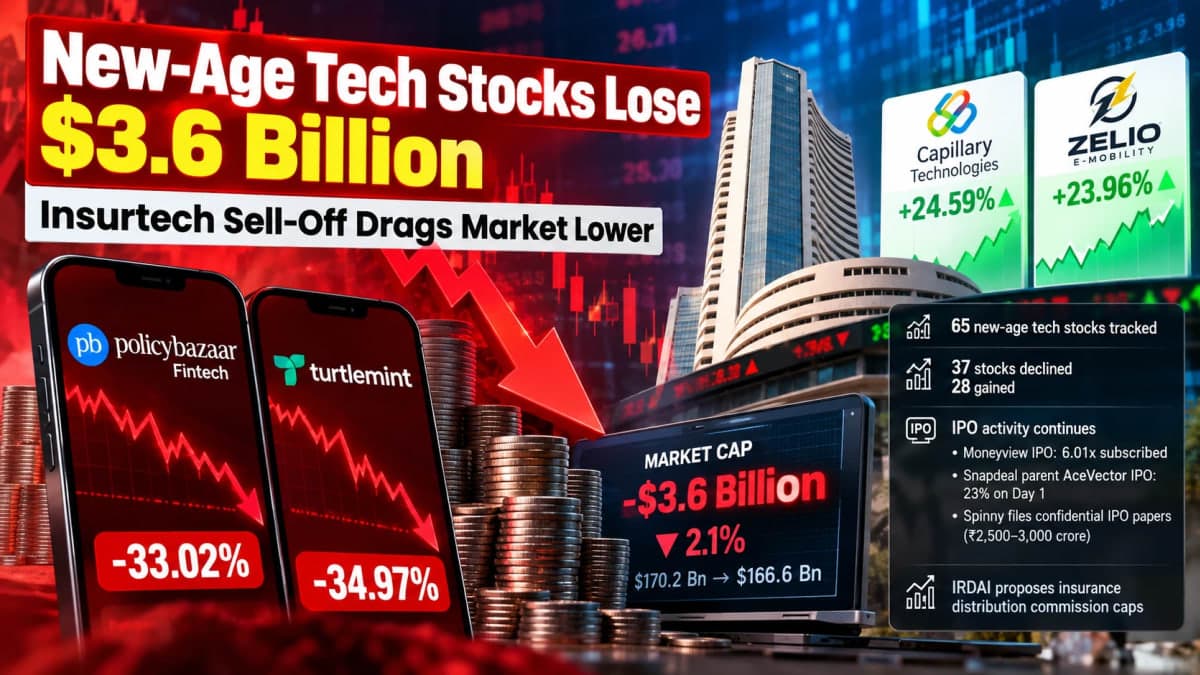
The combined market capitalisation of 65 new-age technology stocks tracked by Inc42 declined about $3.6 billion, or 2.1%, to $166.6 billion from $170.2 billion in the previous week. Of those 65 companies, 37 ended lower while 28 recorded gains.
The biggest pressure came from insurance technology stocks. Turtlemint fell 34.97% over the week, while Policybazaar parent PB Fintech declined 33.02%, as investors assessed the possible implications of proposed regulatory changes to insurance distribution commissions.
Why Did Insurtech Stocks Fall So Sharply?
The sell-off followed a consultation paper from the Insurance Regulatory and Development Authority of India (IRDAI) proposing significant changes to insurance distribution economics.
According to Inc42's analysis of the proposals, IRDAI is considering the return of product-specific commission ceilings, alongside tighter restrictions on insurers' overall expenses and greater scrutiny of indirect distributor incentives.
The proposal is particularly relevant to online insurance distributors because commissions received from insurers are an important component of their business models.
If implemented, lower commission limits could affect distributor revenue and potentially force platforms to reconsider customer-acquisition spending, sales incentives and commercial arrangements with insurers. These remain proposed rules rather than final regulations, an important distinction when assessing their eventual financial impact.
PB Fintech and Turtlemint Lead the Decline
PB Fintech and Turtlemint were among the stocks most exposed to investors' concerns.
During the week covered by Inc42, Turtlemint declined 34.97%, while PB Fintech dropped 33.02%. Inc42 separately reported that PB Fintech lost roughly ₹31,500 crore in market capitalisation in a single session amid the reaction to the regulatory proposal.
The decline does not establish what the companies' eventual financial impact will be. That will depend in part on the final regulatory framework and how companies and insurers adapt their distribution arrangements.
Capillary Technologies and Zelio Move in the Opposite Direction
The weakness was far from universal.
Capillary Technologies emerged as the strongest performer among the stocks tracked by Inc42, climbing 24.59% to ₹603.15. Zelio E-Mobility followed with a 23.96% weekly rise to ₹1,056.90.
Zelio, ESDS, Shadowfax, Nazara and BlueStone reached fresh 52-week highs during the week. In contrast, Shiprocket, IndiaMART, Menhood, Turtlemint and PB Fintech touched fresh lows, while Lenskart, Paytm and Swiggy also finished the week lower.
The divergence shows that the $3.6 billion decline in combined market capitalisation was not a uniform retreat across India's listed startup ecosystem.
37 of 65 New-Age Tech Stocks Finish Lower
The overall numbers nevertheless tilted negative.
Of the 65 stocks tracked by Inc42, 37 declined between 0.01% and 34.97%, while 28 gained between 0.26% and 24.59%.
The weakness also came during a broader difficult period for Indian equities, with Inc42 reporting that benchmark indices registered their seventh consecutive weekly decline.
This broader market backdrop is important: although the insurtech regulatory development was a major company-specific catalyst, the entire new-age technology segment was also trading within a weak overall equity environment.
IPO Activity Continues Despite Secondary-Market Weakness
The sell-off did not bring startup capital-market activity to a halt.
Moneyview's ₹1,092 crore IPO was subscribed 6.01 times by the end of its second day of bidding, according to Inc42. Snapdeal parent AceVector's ₹420 crore IPO recorded 23% subscription on its first day.
Used-car marketplace Spinny also confidentially filed IPO documents with the Securities and Exchange Board of India, with Inc42 reporting a targeted issue size of approximately ₹2,500 crore to ₹3,000 crore.
This creates a notable contrast: investors were aggressively repricing some already-listed technology companies while primary-market activity among newer entrants continued.
Other Major Developments Across Listed Startups
Several company-specific developments added to the week's activity.
ESDS reported Q1 FY27 net profit of ₹29.3 crore, up 14% year-on-year but down 57% sequentially, while operating revenue increased 7.3% year-on-year to ₹133.7 crore and fell 20% sequentially.
Contract manufacturer Aequs approved a proposed preferential warrant issue of up to ₹650 crore, while Ola Electric's board was scheduled to consider a rights issue on September 28.
Meanwhile, Nykaa partnered with L'Oréal's corporate venture capital fund BOLD to pursue minority investments in emerging Indian beauty and wellness brands, with founders retaining operational control.
What Investors Will Watch Next
The most important unresolved factor for the insurtech segment is the eventual form of IRDAI's insurance-distribution rules.
Because the commission restrictions are currently proposals, the consultation process and any resulting final regulations will determine how closely the eventual framework resembles what markets reacted to this week.
The episode nevertheless demonstrates how regulatory changes can quickly affect the valuation of technology businesses whose revenue models depend heavily on regulated financial products.
For the broader new-age technology sector, the contrast between falling insurtech valuations, rising stocks such as Capillary Technologies and Zelio E-Mobility, and continued IPO activity suggests that investors are increasingly differentiating between individual business models rather than treating listed startups as a single category.