India’s Semiconductor Sector Has Raised $1.4 Billion — But the Bigger Story Is Where Half the Money Came From
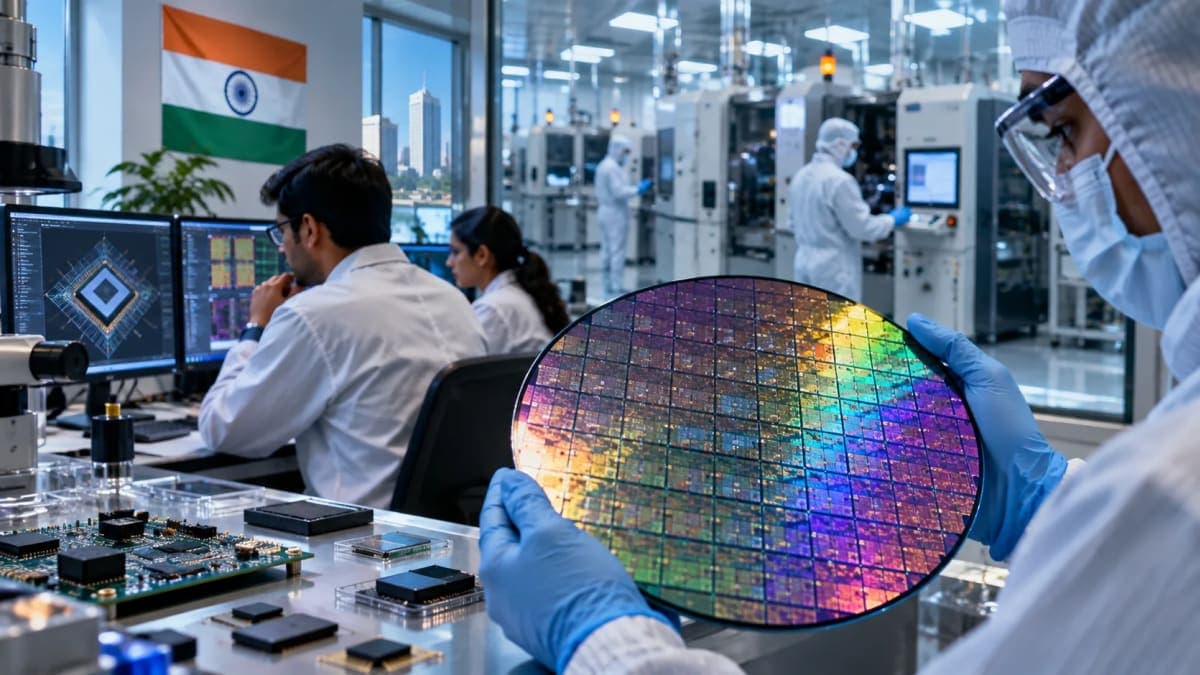
India’s semiconductor ecosystem has attracted around $1.4 billion in cumulative equity funding, but a closer look at the data reveals a more important shift: roughly $701 million has been raised since the start of 2025 alone. According to Tracxn data cited by PTI, semiconductor funding reached $473 million in 2025 and another $228 million has flowed into the sector in 2026 so far. The acceleration comes as India tries to build capabilities across chip design, fabrication, packaging and electronics manufacturing rather than remaining primarily a semiconductor-design talent base.
What exactly does the $1.4 billion figure mean?
The $1.4 billion figure is not funding raised in 2026, nor should it be interpreted as a single recent investment wave.
It represents cumulative equity funding tracked across India's semiconductor ecosystem. Tracxn data cited in current reports refers to 281 funded companies in the sector.
The timing of that capital is more revealing.
Around $701 million has been raised since 2025, representing approximately half of the cumulative total. Of that amount, $473 million came in 2025 and $228 million has been recorded in 2026 so far.
That means the headline number is best understood as evidence of a longer-term ecosystem taking shape, with a pronounced acceleration over the past two years.
Funding has risen sharply from 2021 levels
Tracxn's data shows semiconductor-sector funding rising from approximately $49 million in 2021 to $473 million in 2025.
The reported five-year compound annual growth rate in funding is above 36%.
That comparison gives the $1.4 billion figure more useful context. India is still building a relatively young semiconductor financing ecosystem, but investors are putting significantly more capital into it than they were several years ago.
The increase is particularly notable because semiconductor companies generally face very different economics from conventional software startups. Designing chips, validating silicon, accessing foundries, building hardware, certifying products and moving from prototype to production can require substantial capital and much longer development timelines.
That makes access to later-stage financing especially important as Indian companies attempt to commercialise their designs.
Which semiconductor companies have raised the most?
According to the Tracxn dataset, Tessolve Semiconductor leads cumulative funding at approximately $213 million.
It is followed by:
ILJIN Electronics: about $198 million
VVDN: about $129 million
These numbers also show an important nuance in India's semiconductor story: the ecosystem extends beyond pure fabless chip startups.
It includes semiconductor engineering, electronics manufacturing services, embedded hardware, power-management chips and other companies supporting the wider electronics and chip supply chain.
That distinction matters when interpreting the $1.4 billion figure. It should not automatically be presented as venture funding exclusively for new Indian chip-design startups.
Electronics manufacturing is attracting the most recent capital
Among business models tracked by Tracxn, Electronic Manufacturing Services, or EMS, attracted about $313 million since 2025, making it the largest funded segment during that period.
Embedded hardware followed with approximately $51.9 million, all of which was raised during the trailing 12 months, according to the dataset. Power-management integrated circuits and fabless semiconductor businesses were also among the notable categories receiving funding.
This shows that investor interest is not confined to companies designing advanced processors.
Capital is also flowing toward firms that can manufacture, assemble, integrate and test increasingly complex electronic products.
Bengaluru remains India's semiconductor capital
Bengaluru continues to dominate India's semiconductor ecosystem.
Tracxn identified 626 semiconductor companies in Bengaluru, around 18% of the 3,557 companies in its broader sector database. More significantly, Bengaluru accounts for approximately 40.1% of cumulative semiconductor equity funding.
Noida ranks second by funding share at 16.4%, followed by:
HubShare of fundingBengaluru40.1%Noida16.4%Gurugram10.7%Kochi8.8%Hyderabad6.2%
Bengaluru's dominance is unsurprising given the city's long-established semiconductor design, electronics engineering and global technology R&D base.
But the emergence of Noida, Gurugram, Kochi and Hyderabad suggests India's semiconductor ecosystem is becoming geographically broader.
Government support is trying to solve the early-stage funding problem
Private funding is only one part of India's semiconductor strategy.
The government's original Semicon India Programme carries an outlay of ₹76,000 crore and is intended to build capabilities across fabrication, assembly, packaging and chip design. As of February 2026, the government said it had approved 10 semiconductor projects involving envisaged investment of about ₹1.6 lakh crore, including two fabs and eight packaging-related facilities.
Chip design has received separate support.
Official government data says 24 semiconductor design projects have been approved for assistance. Fourteen of those companies had already raised outside venture-capital funding, collectively raising around ₹650 crore. Seven chips had been successfully fabricated from 16 taped-out designs.
One example is Vervesemi Microelectronics, which raised $10 million in Series A funding in February 2026 after receiving support under the Design Linked Incentive programme. The government said the company had built a portfolio spanning motor-control chips, EVs, drones, avionics and space applications.
This suggests government programmes are increasingly being used not simply as subsidies, but as a bridge between engineering development and private investment.
Why investors are paying more attention now
Several developments are converging.
India already has a large semiconductor engineering workforce, while domestic demand for electronics continues to grow.
Government data shows India's electronics manufacturing output expanded from roughly ₹1.9 lakh crore in 2014-15 to about ₹12 lakh crore in 2024-25, a six-fold increase.
More electronics manufacturing creates greater domestic demand for chips, power-management components, embedded systems, sensors and specialised semiconductor designs.
At the same time, India is trying to reduce dependence on concentrated global semiconductor supply chains by encouraging domestic design, manufacturing and packaging.
The government's Semiconductor Mission 2.0, announced in the 2026-27 Budget, is intended to expand attention toward semiconductor equipment, materials, Indian intellectual property and supply-chain resilience.
For investors, that combination can create opportunities across several layers of the value chain rather than only in full-scale semiconductor fabrication.
But $1.4 billion still needs global context
The funding acceleration is meaningful for India, but it should not be interpreted as proof that India's semiconductor startup ecosystem has already reached the scale of major global chip markets.
Semiconductor development is extremely capital-intensive, and global investment in chip design and AI hardware can run into billions of dollars for individual companies.
For example, U.S.-based AI-chip startup Positron announced an $875 million funding round in September 2026 alone, valuing the company at about $5 billion.
That single transaction is equivalent to a substantial portion of the cumulative semiconductor equity funding tracked across India's ecosystem.
The comparison does not diminish India's progress. Instead, it illustrates how much capital is required if Indian semiconductor companies are to compete globally in cutting-edge chip design and manufacturing.
Another challenge: many Indian chip startups remain unfunded
Funding growth also hides a structural gap.
A recent industry analysis citing Tracxn data estimated that India has hundreds of domestic semiconductor design startups, but only a relatively small share have attracted venture-capital backing.
Official data paints a similar picture from the government-support side. While 24 semiconductor design projects have been approved, only 14 of those companies had raised VC funding at the latest official count.
For many chip startups, the difficult phase begins after designing an initial product.
They then need money for tape-outs, foundry runs, packaging, testing, certification, customer qualification and manufacturing scale.
Those costs can make semiconductor companies harder to finance than asset-light software businesses.
Acquisitions remain the most common exit route
The Tracxn dataset also provides clues about how investors eventually realise returns.
It records 62 acquisitions compared with 42 IPOs across the sector.
Companies that were acquired took an average of around 11.8 years from their first funding round to exit, compared with approximately 16.5 years for IPOs.
The largest recorded acquisition in the dataset was eInfochips at $282 million, followed by Narayan Powertech at $262 million and SmartPlay Technologies at $180 million.
Those timelines reinforce why semiconductor investing typically requires patience.
What should investors and the industry watch next?
Three developments will matter more than the headline funding total.
First, whether Indian semiconductor companies can progress from prototypes to commercially shipped chips and systems.
Second, whether later-stage funding increases. Seed capital can help produce a design, but scaling a semiconductor company globally often requires much larger rounds.
Third, investors should watch whether Indian intellectual property remains with domestic companies as consolidation increases.
India's semiconductor opportunity will ultimately be measured less by the amount of capital announced and more by how many companies turn that capital into manufacturable products, sustained revenues and defensible semiconductor IP.
What the $1.4 billion number really tells us
The correct interpretation is not:
“Indian semiconductor startups raised $1.4 billion this year.”
That would be inaccurate.
A more precise interpretation is:
India's broader semiconductor ecosystem has attracted roughly $1.4 billion in cumulative equity funding, with approximately $701 million — nearly half — arriving since the beginning of 2025.
That acceleration is the real story.
It suggests investor appetite for India's semiconductor and electronics ecosystem is increasing, but the next test will be whether funding translates into Indian-designed chips, commercial scale and globally competitive semiconductor companies.